



Business leaders entering 2026 are unlikely to face one single supply-chain condition. They are more likely to manage several at once: stable supply for mature items, uneven availability for specialized components, volatile freight or trade costs on selected lanes, and demand signals that change faster than procurement cycles. For industrial buyers, the practical question is not whether supply chains will become “resilient.” It is which exposures justify investment before a disruption turns into a production, margin, or customer-service problem.
Supply chain trends 2026 point toward a more selective form of resilience. Broad supplier diversification and larger inventories remain useful tools, but neither is sufficient on its own. A second source that shares the same material origin, production geography, tooling dependency, or shipping corridor may offer little protection. Likewise, higher inventory can protect delivery performance while quietly increasing obsolescence, working-capital pressure, and quality risk.
The strongest planning approach is scenario-based: identify the supply lines that would materially damage the business if interrupted, define the conditions under which they fail, and decide in advance what commercial, technical, and operational response is realistic.
Resilience in 2026 Will Be More Product-Specific
Companies with mixed product portfolios should resist applying one sourcing rule to every purchase category. Standard fasteners, common packaging formats, basic stationery materials, and widely available hardware may have broad supplier pools. Yet a seemingly ordinary item can still become critical when it is tied to a specific finish, certification, thread standard, adhesive formulation, mold, or customer-approved bill of materials.
Electromechanical components illustrate the distinction. A motor, bearing, pump part, or electrical subassembly may be technically substitutable in principle, but qualification can require dimensional checks, safety documentation, field validation, controller compatibility, or customer approval. The commercial availability of alternatives does not mean the business can switch without interruption.
Industrial adhesives and sealants create a similar challenge. A replacement may match the broad application description while differing in cure profile, viscosity, bonding performance, emissions profile, storage requirements, or interaction with substrate coatings. Packaging films can be changed more quickly in some applications, but a change in gauge, sealing window, print behavior, barrier performance, or recyclability claim can affect line efficiency and downstream compliance commitments.
The planning unit therefore should not be “supplier count” alone. It should be a critical item or material family linked to its actual production and sales consequences. Decision-makers need a view that combines:
- the item’s contribution to finished-product revenue or customer delivery commitments;
- the time required to qualify an alternative source, material, or specification;
- the concentration of production, tooling, and upstream inputs behind existing suppliers;
- the inventory that is genuinely usable, rather than inventory awaiting inspection, allocation, or conversion;
- the cost of a delayed shipment compared with the cost of maintaining protection.
This changes the discussion from “Do we need more suppliers?” to “Which supply dependencies can we actually recover from, and within what time frame?”
Plan Around Failure Modes, Not Headlines
Trade policy changes, regional conflicts, port congestion, energy costs, currency movement, and raw-material volatility all matter. But broad news events are not a planning model. Their effect varies by product structure, contract terms, route, lead time, and the degree to which a supplier can absorb or pass through cost.
A useful 2026 sourcing plan can be built around three operating scenarios rather than a long list of external forecasts.
Scenario One: Cost Moves Faster Than Demand
In this scenario, material, freight, duty, energy, or financing costs rise while customer pricing remains fixed or slow to adjust. The immediate risk is margin erosion, especially on high-volume, specification-sensitive products where a buyer cannot readily substitute materials or renegotiate supply terms.
For hardware, fasteners, packaging, and adhesive categories, leaders should identify where the price quoted by a direct supplier masks upstream exposure. A supplier may have a stable unit price today while relying on one resin grade, metal input, coating chemical, paper stock, or imported subcomponent with a different pricing cycle. The aim is not to predict every increase. It is to understand which contracts include review mechanisms, what triggers a cost discussion, and how much lead time is available before margin pressure reaches the finished product.
Commercial responses should be prepared before a price event: alternate specifications already approved for non-critical customers, volume commitments that earn meaningful priority or price protection, index-linked clauses where appropriate, and a clear internal threshold for when sales pricing must be reviewed. Without those decisions, procurement is often asked to solve a margin problem after the available options have narrowed.
Scenario Two: Supply Is Available, but Lead Times Become Unreliable
This is often more damaging than a visible shortage. Suppliers continue accepting orders, yet transit time, production sequencing, customs clearance, or component allocation becomes inconsistent. Planning systems may show sufficient pipeline inventory while manufacturing faces gaps because deliveries arrive in the wrong order.
For this scenario, average lead time is a weak planning measure. Procurement teams should examine lead-time variability: the difference between the expected date and the actual arrival window. A component with a nominal six-week lead time may need a much larger planning buffer if deliveries regularly move between four and ten weeks. The buffer should reflect the cost of a missed production run, not simply an old safety-stock formula.
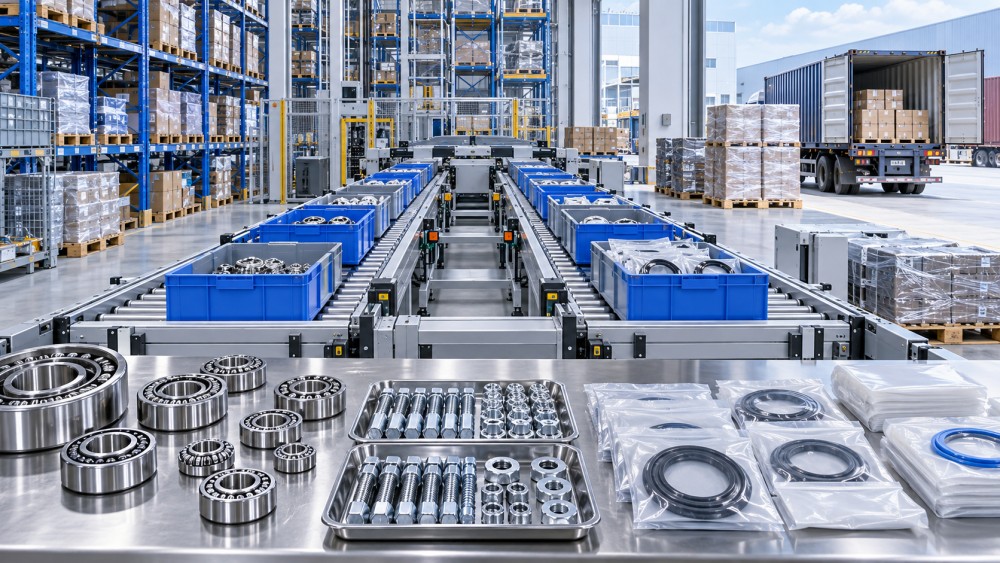
Visibility also needs to extend beyond shipment tracking. Leaders should know where orders are in the supplier’s process: raw material secured, production slot confirmed, goods completed, quality released, export documents ready, and freight booked. Each status points to a different intervention. Escalating an order that has no material allocation is very different from expediting finished goods awaiting a vessel booking.
For priority components, the most effective safeguard may be capacity and schedule discipline rather than more stock. This can include locked production windows, supplier-held buffer stock with defined ownership, split shipments for high-risk orders, or agreed escalation paths when delivery dates move outside a specified range. These arrangements work only when demand forecasts and purchase commitments are credible enough for suppliers to plan against them.
Scenario Three: A Supplier Remains Operational but Cannot Meet the Required Specification
Supply continuity is sometimes treated as a quantity issue. In industrial categories, quality and conformity can be the actual constraint. A supplier may ship on time but fail to maintain plating consistency, packaging performance, adhesive batch stability, dimensional tolerance, labeling requirements, or a customer-mandated material declaration.
This risk becomes sharper when companies change source quickly. Emergency purchasing can introduce variation in substrates, coatings, component tolerances, shelf-life controls, or documentation practices. The resulting defect may appear after assembly, printing, installation, or end-customer delivery, where correction costs are far greater than the original supply saving.
Resilient sourcing therefore requires a pre-defined substitution path. For each critical item, teams should distinguish among alternatives that are technically identical, alternatives requiring limited process adjustment, and alternatives that need formal requalification. The classification should be owned jointly by procurement, engineering, quality, operations, and commercial teams. Procurement cannot determine interchangeability from a quotation alone.
Supplier Diversification Has Limits
Adding a second supplier is frequently presented as the default answer to supply risk. It can reduce exposure, but its value depends on independence. Two suppliers located in different cities may still buy from the same mill, compounder, component maker, tool shop, logistics consolidator, or parent group. Conversely, a supplier in the same region may provide useful resilience if it has separate inputs, flexible capacity, and a proven ability to serve the required specification.
Decision-makers should test diversification with a small set of practical questions:
- Does the alternate source rely on the same upstream material, subcomponent, tooling, or transport route?
- Can it meet the required specification at production scale, rather than only provide samples?
- What capacity is genuinely uncommitted, and how quickly can it be assigned?
- Are drawings, test requirements, packaging instructions, and change-control expectations clear enough to support a switch?
- Would the alternative create a new exposure in intellectual property, payment terms, documentation, or regulatory compliance?
There is also a cost to maintaining optionality. Low-volume orders spread across many suppliers can weaken purchasing leverage, complicate quality management, and reduce a buyer’s priority during constrained periods. For some categories, a better approach is a primary supplier relationship supported by a qualified contingency source, with periodic validation rather than continuous volume splitting. For others, especially where supply is standardized and switching costs are low, dual sourcing can be active from the start.
Inventory Strategy Should Separate Protection From Convenience
Higher inventory is easy to justify after disruption and difficult to unwind afterward. By 2026, businesses will need a more disciplined distinction between inventory held for resilience and inventory accumulated because planning, purchasing, and demand signals are misaligned.
Protection stock is tied to a defined risk: a long qualification period, a concentrated supplier base, an extended inbound route, a seasonal capacity bottleneck, or a high consequence of line stoppage. Convenience stock has no clearly stated trigger or recovery objective. The first can be defended as an operating decision. The second often becomes a hidden cost that masks weak forecasting or supplier communication.
Segmentation matters here. A long-life standard screw can often tolerate a deeper buffer than a shelf-life-sensitive adhesive, a printed packaging material tied to a seasonal design, or a component exposed to rapid model changes. The economic question is not simply whether a unit is cheap. It is whether the inventory remains usable if demand, specifications, or customer requirements change.
For each protected item, leaders should define the disruption it is intended to cover and the point at which stock should be replenished, released, or reduced. This prevents resilience inventory from becoming permanent excess stock without an owner.
What to Monitor Before It Becomes an Escalation
Many supply-chain problems are visible early, but the signals sit in separate functions. A buyer sees repeated quotation extensions. Quality sees a rise in minor deviations. Logistics sees missed booking windows. Sales sees customers adjusting forecast patterns. Finance sees suppliers requesting shorter payment terms. No single indicator proves that a disruption is coming, yet the combination can justify earlier action.
A compact executive review should focus on exceptions rather than every purchasing metric. Useful questions include whether any critical item has lost its qualified alternative source, whether supplier confirmations have become less reliable, whether inventory coverage depends on overdue purchase orders, whether an upstream material change has been proposed, and whether the business can still meet its customer commitments under a delayed-delivery scenario.
The purpose is to make trade-offs explicit. Carrying more stock, qualifying a regional source, accepting a higher unit cost, redesigning a component, or changing customer lead times are different decisions with different owners. Treating all of them as a procurement task usually delays the decision until operational choices have become expensive.
Build Decision Rights Before the Next Disruption
The most practical supply chain trend for 2026 is organizational rather than technological: faster decisions will depend on clarity established before pressure arrives. A company should know who can approve an alternate material, authorize a premium freight movement, accept a temporary cost increase, reallocate constrained supply among customers, or release contingency inventory.
That governance must be paired with clean product and supplier data. Part numbers, approved specifications, revision control, supplier site details, country-of-origin information, lead-time assumptions, and available substitutes are basic operating records. When they are incomplete, teams spend the first days of a disruption arguing about facts rather than deciding what to do.
Resilient sourcing in 2026 will not come from trying to eliminate every risk. It will come from recognizing which dependencies matter, designing realistic responses for them, and reviewing those assumptions often enough that the plan still reflects the products, suppliers, and markets the business actually relies on.
Related News
- 00
0000-00
How to verify whether industrial bolts meet the ISO standard - 00
0000-00
When do water-based adhesive technologies for packaging make sense? - 00
0000-00
What to compare in a solution comparison tool before choosing a vendor - 00
0000-00
When does lifestyle product sourcing make sense for home stores? - 00
0000-00
When high strength bonding technology outperforms mechanical fasteners
Weekly Insights
Stay ahead with our curated technology reports delivered every Monday.